

Editor’s note: This article was first published in May 2011; its reference to funds recommended before and after the Japan earthquake points to March 2011, and its mention of the economic collapse refers to the 2008 financial crisis.
Imagine you’re one of those people who have some money put aside, and you know that if you don’t invest it, that idle money won’t earn you anything. You’re convinced you need to put your money to work and, above all, invest it.
Now, let’s imagine you turn to people who will look out 100% for your interests at all times (which, in some cases, is a lot to imagine). We’ll see why, even when you invest through a professional, whether your bank manager or a specialist financial adviser, with all the good intentions in the world, your money can be put at risk.
I’ll use myself as an example. My family and friends know what I do for a living, they know I’ve been investing in the stock market for many years and, above all, they know my track record (which, thank God, has been good so far).
These people sometimes ask me for advice on investing amounts of €5,000, €10,000 or a little more. Of course they’re looking for quick money, ideally a high return within six or seven days, and I always explain that they need to be prepared to do without that money for a year or more if things go wrong.
As a rule, even though I’m not keen on giving advice on where to invest money that isn’t mine, I usually tell them to wait for my call, which may come in 2 days, 5 days or 60 days, because I’ll advise them to get in at the same moment and in the same stock as I do. I earn nothing from the advice, and if the “move” ever went wrong, I could even fall out with a friend for having pushed them into a bad investment.
Now let’s imagine I’m a professional who makes a living from this. I invest other people’s money. I’d run into the following problems.
The first problem. If I see 50 clients over the week and advise all of them to buy the same stock, and my “prediction” fails, I’ll have 50 unhappy clients. So it’s only human to send a percentage of them towards another stock to spread the risk of my “stock market predictions.” The problem for you is that I may have sent you towards a second card that wasn’t the one I had in mind, and one I don’t like as much as my first choice.
The second problem. As a private investor, I know how important it is to choose the right moment to buy into a stock, and that it takes patience. I may like a share but consider it still too expensive, and think it’s only a matter of days or weeks before its price drops and I find the ideal moment to get in and make a quick profit.
If, as a private investor, I know that not every moment is a good time to buy, why would I, as a financial adviser, always have a stock ready to recommend to you? Simply because it’s my job, and I know you’re in a hurry to invest and that, if you don’t do it with me, you’ll do it with someone else. That rush to win you as a client can lead me to invest your money badly. With a bit of luck, the “casino bet” we’ve placed comes up red and we win, but black is always a possibility.
All of this assumes I’m acting in good faith. Normally, when you walk into an asset manager, financial adviser or bank, they already have the product they’re going to offload on you before you even come through the door, because they get a nice bonus for selling it to you. That’s why they were recommending the same investment funds before and after the Japan earthquake, even though buy recommendations changed in those days.
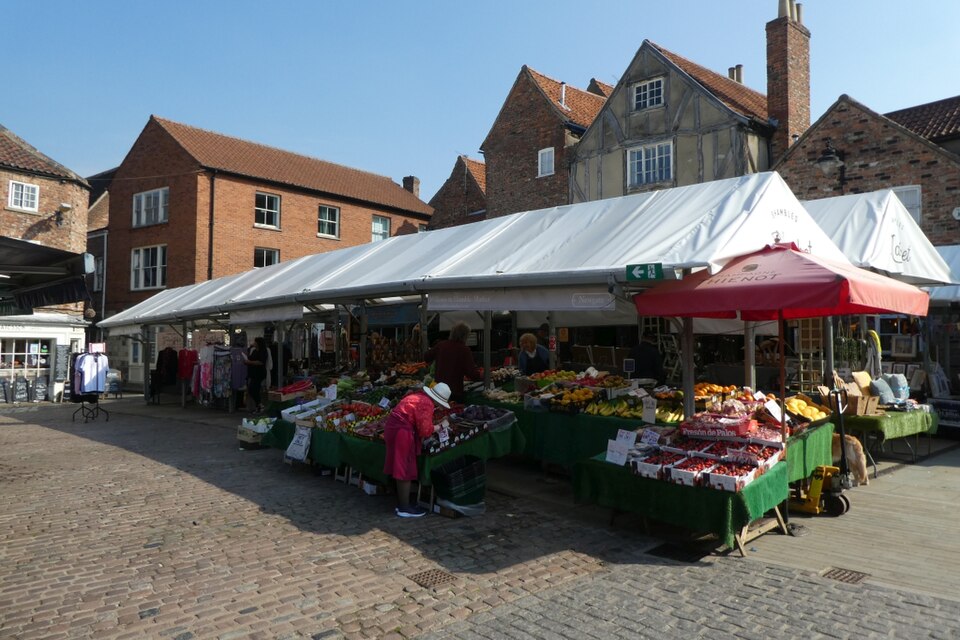
An even clearer example is to compare a bank with a market. At the market there’s fresh fruit and fruit that’s starting to rot. If I let it rot, I’ll lose money, so among 12 pieces of fresh fruit in your basket you won’t notice that I’ve slipped in two rotten ones. Sometimes my boss has even told me to hide the fresh fruit until I’ve got rid of everything that’s about to go bad.
On top of that, we’ve been sent some new products to sell alongside the fruit that give us a very good margin, so, like a good salesman, I’m going to offload one of those on you too.
The €10,000 you bring me is a lot for you (your life savings), but for me it’s nothing, so I don’t need to keep you particularly happy. I am, however, waiting for someone who’s coming in after you to invest €300,000, and that’s the one I want to keep happy. So with ten more like you I’ll get rid of the rotten fruit, and then I’ll bring out the freshest fruit.
What’s more, with the possible losses of ten people like you, I’ll make sure to fatten the returns of that other “deluxe client.”
What some may find appalling happens every day. In fact, without looking any further, the economic collapse we went through was caused because the fruit baskets at the market held more rotten fruit than fresh. Whoever poisoned the consumer is still selling fruit, and it tends to be the fruit you buy when you ask for investment advice. That’s why you should go to the market yourself and examine the fruit you like.
Featured image: Fruit stall on the market by DS Pugh, CC BY-SA 2.0, via Wikimedia Commons.



