

Editor’s note: This article was first published in November 2012. It is market commentary from 6 November 2012: the prices, supports (€2.57, €2.50, €2.00), targets (€3.00-3.15), the class A/B share swap and the Spanish energy reform all refer to that week.
After the disastrous swap of class A shares for one new share plus four rights exchangeable for class B shares, Abengoa left investors deeply confused. At first the information was so scarce and incomplete that even brokers seemed somewhat lost. The advice was to buy rights rather than shares, but in the end the rights and both the class A and class B shares have all plunged.
Since the swap (which was followed by a 60% jump and a temporary trading halt), Abengoa has closed in the red every session. In theory buyers should have stepped in by now, and some research firms recommended exactly that. But of course: we buy Abengoa, but… do we buy class A or class B shares? It’s another source of confusion that doesn’t exactly encourage anyone to get into the stock.
Technically, the stock is sitting in what we could consider a support zone, at €2.57. If it loses that support (€2.50), it could easily head towards €1.80 or even €1.65, unless the psychological barrier of €2 stops it.
The company shouldn’t have much trouble getting back to €3–3.15 in the short to medium term, although the strength of today’s selling, which gave it no respite despite the announcement that it will build two plants in South Africa, is somewhat worrying.
On fundamentals, Abengoa operates in a sector that is not going through its best moment, although the Spanish government’s energy reforms will ultimately not hit it as hard as first expected. Abengoa’s other burden is its high debt (6 times EBITDA). Even so, it’s a company I personally like and one worth adding to the portfolio, but we have to wait for its steep, continuous decline to end.
Once the punishing sessions are over, it could be a very profitable investment in both the medium and long term, with a medium-term target of €3.15. Remember that before this share conversion began, some research firms claimed Abengoa could double its market value within one or two years. So, patience until we see how the stock develops.
Further reading
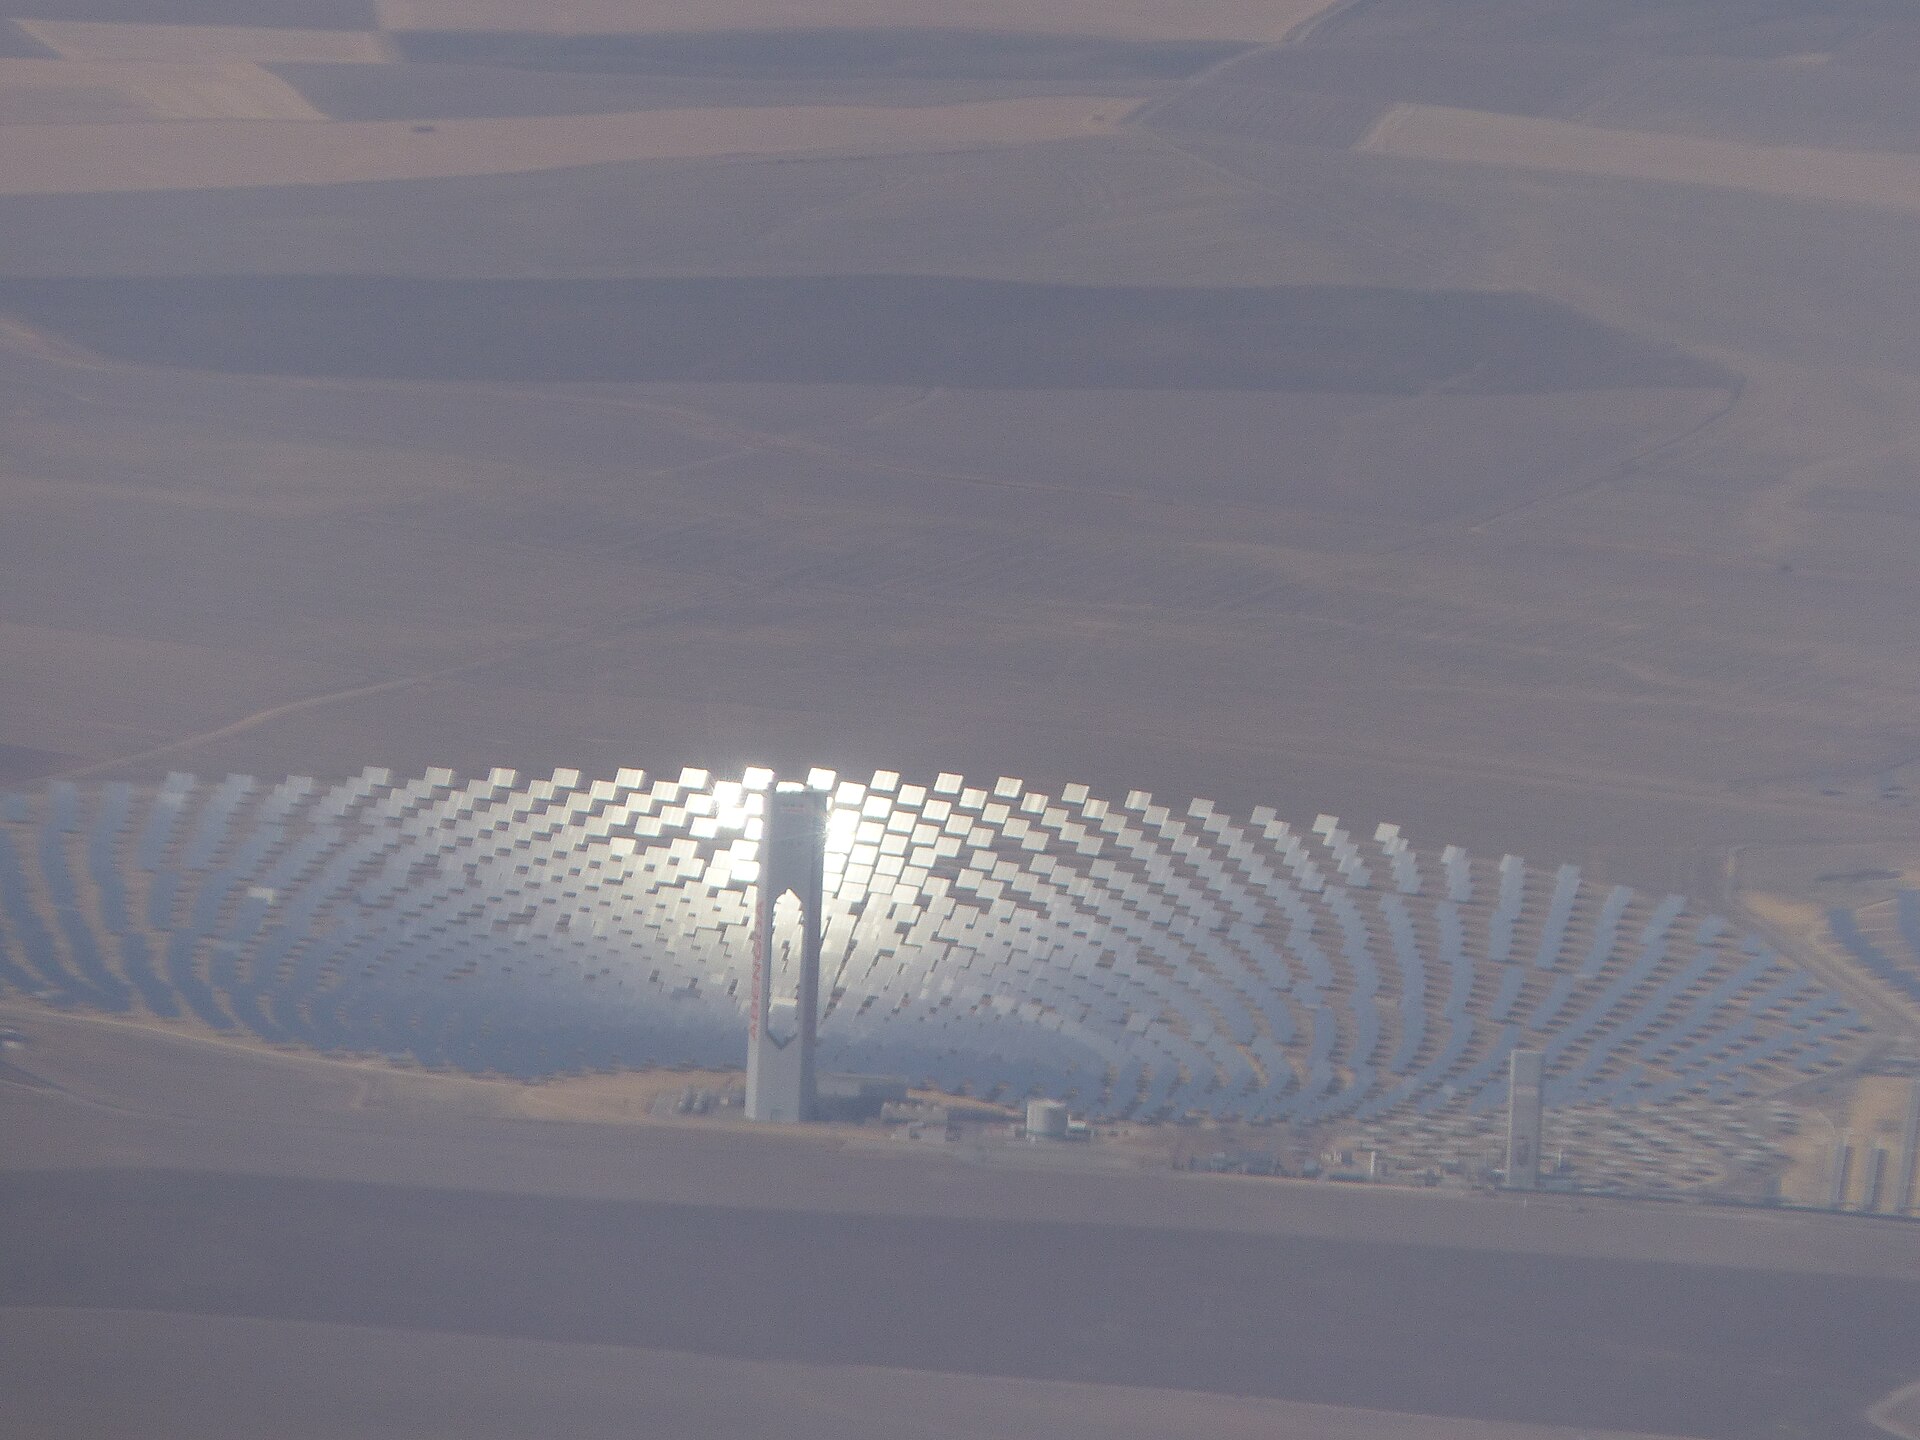
Featured image: Benjamín Núñez González, CC BY-SA 4.0, via Wikimedia Commons.



