

Fifteen years of research at meQuilibrium led psychologist Andrew Shatté, author of The Resilience Factor, to conclude that when it comes to money, people tend to fall into certain psychological traps, especially when they’re short of it. Whether you’re building an emergency fund or dealing with a recent financial setback, Shatté’s main aim is a philosophy for changing negative thought patterns, reducing stress and trying to find balance in life.
(Read also: 7 psychological traps that can hold back your success in business and your career)
Below, Shatté shares four common thinking traps around money, and says that retraining your brain to focus properly on your finances isn’t that complicated.
1. Personalising or externalising the financial problem
When a financial problem comes up, we tend to look for someone to blame. You may think the whole problem is entirely down to what you (and only you) did and caused (personalising), or you blame everything and everyone around you instead of taking responsibility for the problem (externalising).
Shatté says that in these cases the approach can’t be “all or nothing”. Personalise to the extreme and we can end up feeling like complete idiots, sinking under all the blame. Externalise all the blame and we let ourselves off the hook for any mistake on our part, so we never learn from our own errors.
Shatté advises analysing why the financial disaster happened. If you think it was entirely your fault, ask yourself how others also contributed. If you think it was all down to others, look for your own share of the blame too.
That said, as a rule, when a personal financial disaster happens, it’s almost always our fault, because of the wrong decisions we made or because we didn’t see what was coming. But above all, remember that there’s always a way out, and falling apart solves nothing.
2. Magnifying and minimising
There’s a very common human tendency to magnify the bad and minimise the good. According to Shatté, our brain is drawn to the negative. For example, say we set ourselves a financial goal of saving €500 a month for two years towards the deposit on a home. After three months, most people focus on the €10,500 they still have to save, with a feeling of “I’m never going to get there”.
Few people focus on the €1,500 they’ve already closed towards their savings goal. This negative thinking about long-term financial goals is what puts the brakes on building wealth: everyone wants to be rich NOW, and nobody has the patience to build it bit by bit. This short-term thinking is also why most people don’t make money in the stock market.
3. Overgeneralising, or getting the wrong impression
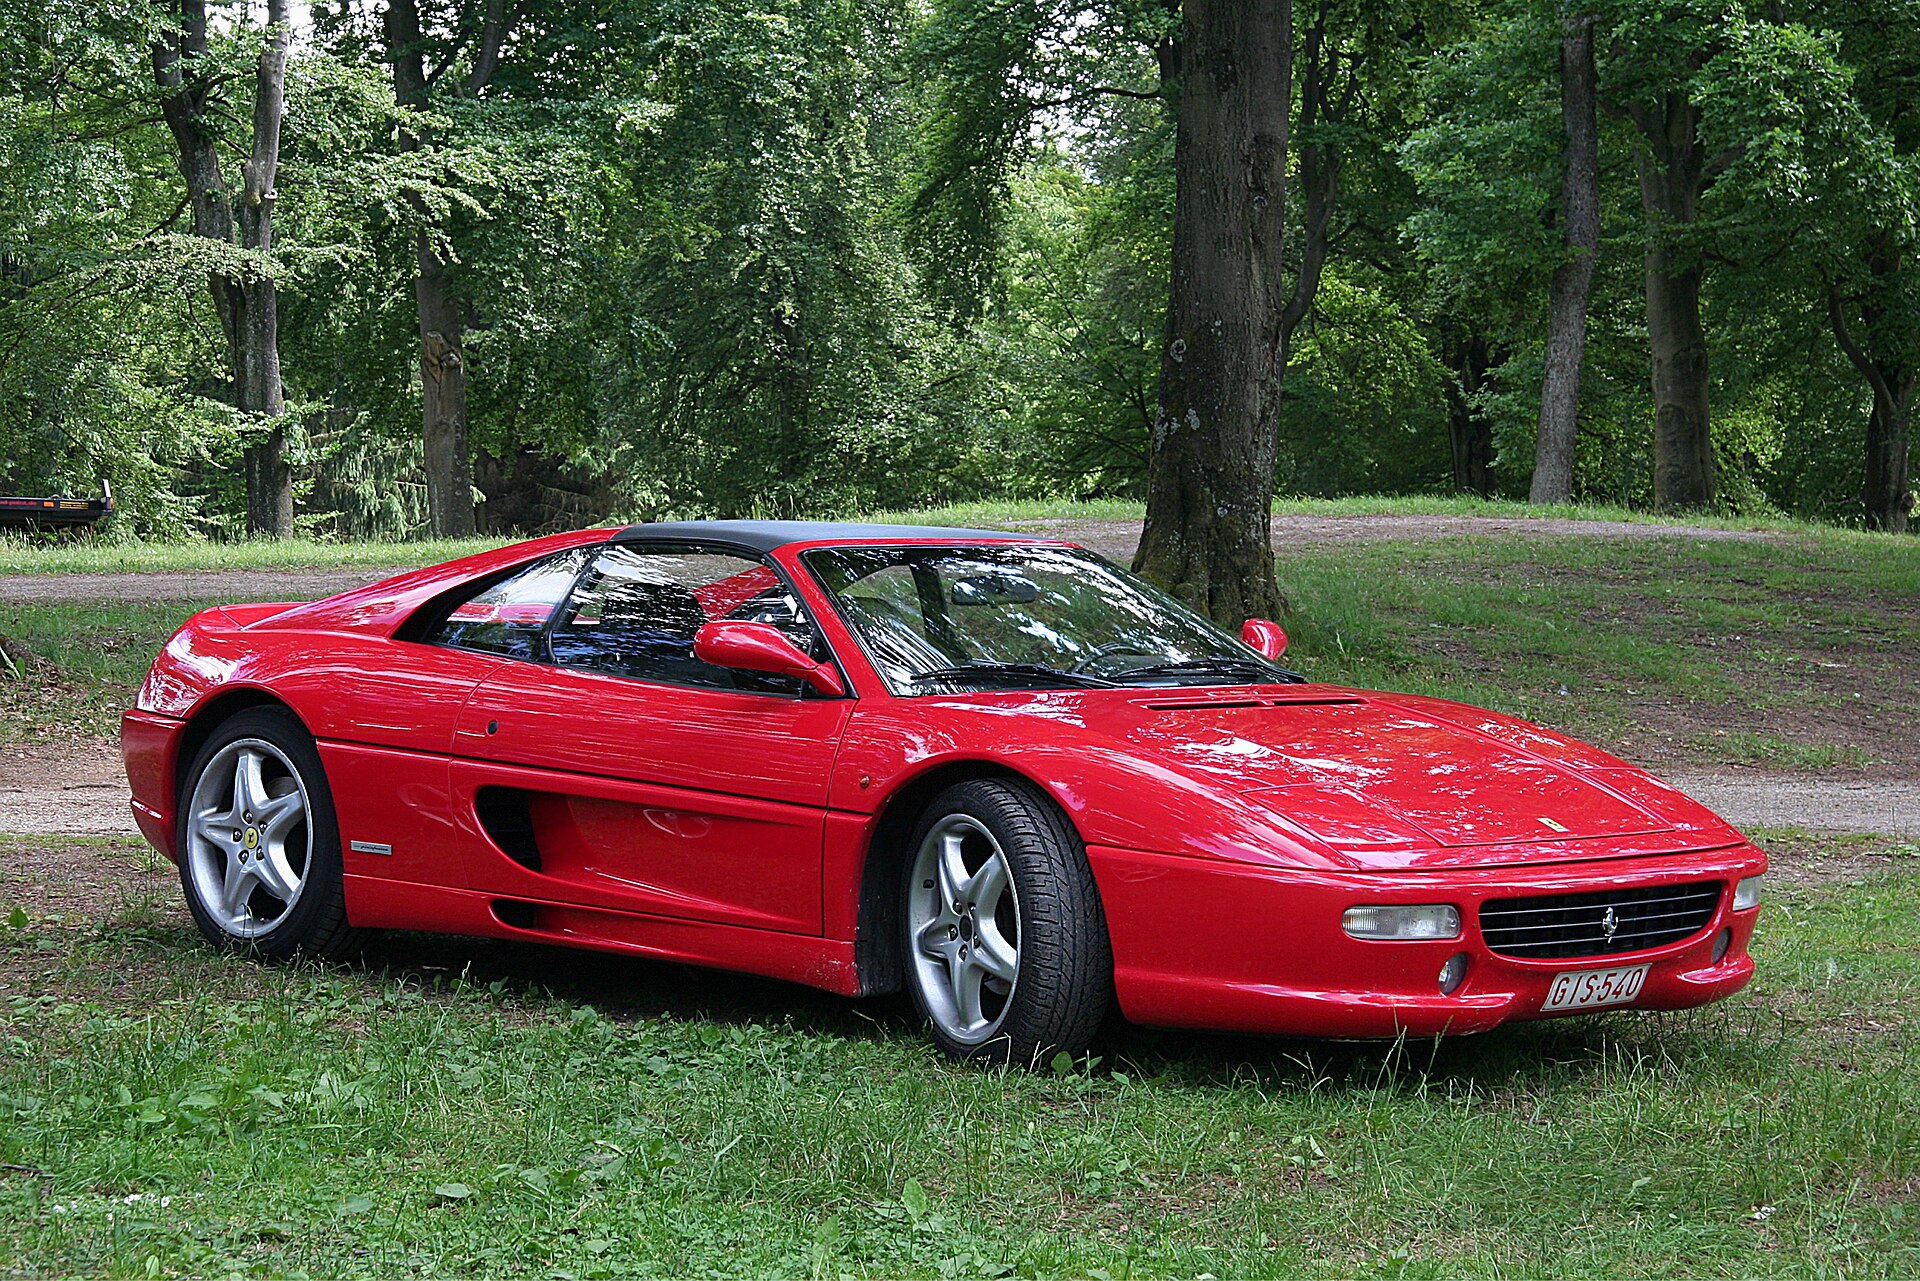
Suppose you see a parked Ferrari. Without realising it, you assume the owner is richer than you, lives in a luxurious house and probably has everything they want in life. “Why is that person so lucky in life, and why am I so unlucky that I struggle to make it to the end of the month?” It’s a very common question.
Now let’s think about who might be behind that Ferrari. That person could have negative finances, like so many idiots who, when they make some money, decide to buy a Ferrari to show what they’ve achieved. Perhaps his finances are hanging by a thread and he’s a businessman whose company can’t pay its suppliers. He might even be married to a beautiful woman 20 years younger who fell in love with the Ferrari rather than its owner, and who takes every chance she gets to sleep with other men who don’t have a Ferrari but do have a bigger engine, so to speak.
Remember that the truly rich don’t like to draw attention to themselves.
(Read: 8 habits millionaires share)
4. Extreme pessimism blinds reason
Imagine you hear rumours that your company is going to cut staff. At that moment, your mind decides that you’ll be one of the people laid off and that, the way things are, you won’t find work for a long time, you won’t be able to pay the mortgage, your wife will feel she married a failure of a man, she’ll leave you, and you’ll only see your children on Tuesdays and every other weekend.
This is called “catastrophic thinking”. It isn’t productive at all, and it often brings about the very situation you’re imagining. What’s more, you can sink before the ship even hits the iceberg.
(Read: How to prepare for a personal financial crisis)
For a start, as a rule, women don’t usually leave their husbands in this situation. Quite the opposite: they tend to become a strong source of support, especially if you didn’t have a Ferrari, because believe me, very few women fall in love with a Seat Ibiza (a modest Spanish hatchback).
When you hear those rumours, you need to prepare: instead of worrying, get busy looking into other options just in case, and build up your emergency fund in case you go without income for a while.
Above all, remember that our mind can be our greatest ally, but it can also become our worst enemy. We’re neither as dumb as we sometimes think nor, certainly, as smart as we often believe. What our mind perceives sometimes has nothing to do with reality, so we need to understand how the unconscious part of our brain works in order to make the most of it.
This article was inspired by a LearnVest post and has been completely rewritten and adapted.
Further reading
- 11 thoughts about money that will change the way you see it
- 10 money and finance tips to follow in your 20s
- 7 psychological reasons people act foolishly with their money
Featured image: Lothar Spurzem, CC BY-SA 2.0, via Wikimedia Commons.



