

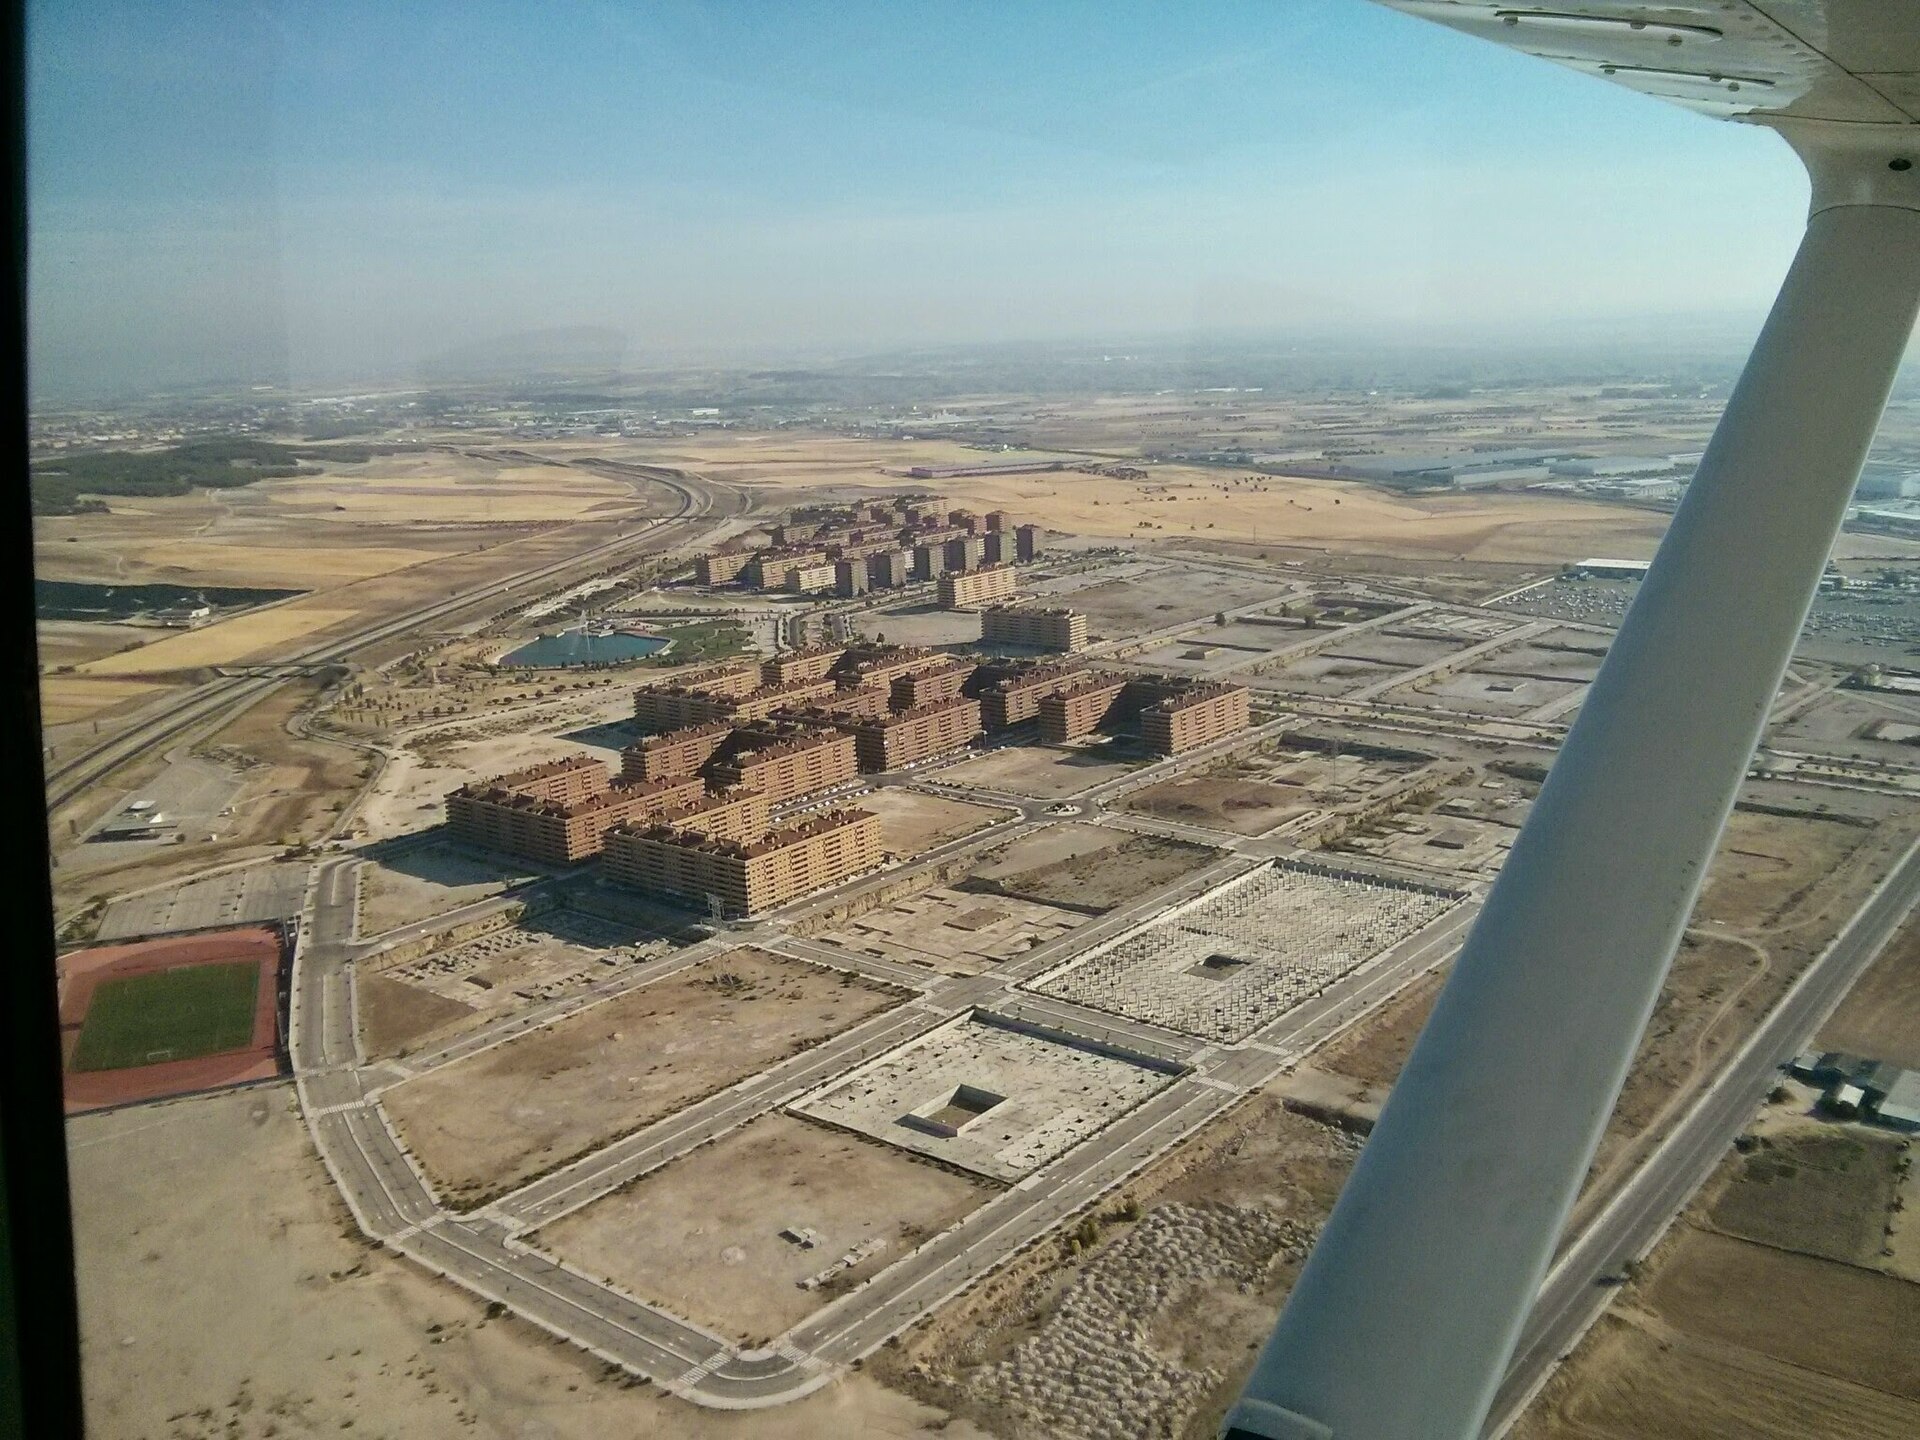
Editor’s note: This article was first published in June 2014, and its remark that it may be a good time to buy, with low prices and very low monthly payments, refers to the Spanish property market in mid-2014. Its example of homes failing to sell at €50,000 while €800,000 properties sold refers to the post-2008 crisis years.
Taking on debt early in life is one of the ways to commit financial suicide. Buying a home with a mortgage is probably the biggest financial commitment we will ever make, so it is the kind of “investment” we should analyse down to the last detail before deciding. At the other extreme there is another view: at first glance, renting a home is throwing money away.
The reasoning behind this feeling is very simple: “we’re paying for something that isn’t ours and never will be.” Ironically, we don’t apply this reasoning when we buy a car. Buying a car really does mean paying for something that sooner or later won’t be yours.
A car is the biggest depreciating asset there is, and over the long term its value tends towards €0. Some will say that a car is an asset that gives us the mobility we need to work. That is completely true, just as renting (seen from that angle) is also an asset that doesn’t tie you down if you need to move to another province or city for work.
So when should we buy and when should we rent?
To answer this question, we draw on a Business Insider article in which Mary Beth Storjohann, a financial planning expert, gives some advice, which we will adapt to the Spanish market, adding our own point of view.
There is no universal answer, because circumstances vary enormously, as does the property price cycle. What there is, though, is a set of questions we should all ask ourselves before taking the plunge.
First, as we have said many times, a young person should under no circumstances take out a mortgage, because it kills their chances of building wealth through saving, investing and reinvesting (compound interest).
Second, buying a home to live in is very different from buying one as an investment.
If it is a home bought as an investment, we should analyse it as if we were buying shares, looking only at the P/E ratio of the investment (in this case the property): working out, realistically, how many years it will take to recover what we put in. Although analysts don’t agree, we could say that a P/E above 20 (20 years to recover our investment) is already high.
If it is a home to live in, you should under no circumstances sign a mortgage (a financial commitment) with a term of 25 to 30 years.
1. Can you afford it?
You could probably make the mortgage payments today, but what about tomorrow? Remember that being able to pay for something doesn’t mean you can really afford it. You also need to know all the costs that come with a home, because it isn’t just the monthly mortgage payment. We’re talking about maintenance, furniture, community fees (if there are any), taxes and unexpected costs such as repairs and breakdowns. Remember how important an emergency fund is? Well, if you buy a house, that fund needs to be even bigger.
Storjohann points out that if you don’t do your homework, you could make the wrong decision and regret it later.
Rent if you don’t have enough for a down payment that brings the mortgage term below 20 years while still keeping enough savings to cope with major unexpected expenses.
Buy if you meet the requirements above and the ones we set out below.
2. Are you financially secure?
Remember that having a job today doesn’t always mean you’ll have one in the future. In fact, one of the requirements for becoming unemployed is having a job. So let’s look beyond simply having a job.
To have some degree of financial security, besides the obvious need to have your finances in order now, you need a stable income and, ideally, several sources of income. You should be free of other debts, or have very little debt.
If you’re thinking of buying a house and you have €1,200 unpaid on a credit card, you’re fooling yourself. Ideally, you should be free of other debts when you buy a home, because the mortgage and the running costs of the home will stretch you to the limit.
Ideally, you would also have some kind of passive income from share dividends or other sources. And clearly, as financial planners point out, they would not advise anyone to buy a house unless they still had an emergency fund left after the initial costs of the purchase.
Rent if buying would wipe out your savings completely and the points above have made you hesitate.
(Read: 10 ways the rich think differently from everyone else)
3. What are your financial goals?
If you’re thinking of starting a business and buying a house, you should do only one of the two: start the business first and put off buying a home for a few years. If the stock market has suffered a spectacular fall and share prices are at rock bottom, it might pay to wait and take advantage of the upswing that would follow, because big stock market crashes happen only a few times in a lifetime. We’re not talking about mere corrections, but major economic crises.
Rent if you’re trying to prioritise other financial goals.
4. Where do you see yourself in the near future?
If you’re unsure where you’ll be in the near future, you should have doubts about whether buying a home makes sense.
Rent until you’re clear about where you’re going to be.
5. Emotions aside, does buying the home make financial sense?
Buying a home is usually an emotional decision, and people rarely look for financial sense in it. That’s why people tend to buy a home when they get married or plan to, as if it were the next prescribed step.
We need to be able to set emotions aside and think about it financially.
Location, with an eye to selling in the future. Even in good times for housing, not all homes gain value equally or have the same chances of selling. Buying in a city centre or a nearby neighbourhood (even if we pay a bit more) is not the same as buying a house in a village simply because it was cheap.
For example, in the middle of the property crisis many owners have been unable to sell their homes for €50,000, while properties priced above €800,000 have sold without any trouble.
We should look at how the area around our home is likely to improve in the coming years: for example, whether there is a plan to build “something” that would make our home gain more value in the future, and also, I insist, the state of the market.
Right now, it’s true that it may be a good time to buy if your finances are healthy and you meet many of the requirements above, because prices and bank terms are such that you can buy a home with incredibly low monthly payments.
The main reason a young person should under no circumstances buy a home
A mortgage payment creates an obligation. You can buy less bread, fewer oranges or fewer eggs, but the mortgage has to be paid, or you put your investment at risk, and probably your guarantors’ assets too. That obligation means, first of all, that you don’t take risks. And if you don’t take big risks, you may not find big rewards.
You couldn’t afford the luxury of losing all your money on an investment and starting again from scratch. But the main reason you shouldn’t buy is simply that the money you would put towards a down payment and then the monthly mortgage payments ought to be generating more money in some kind of investment.
Further reading
- This is how much you need to save to retire with 1 million
- The difference between starting to save at 25 and at 35
- 5 money conversations to have with your partner before getting married
- The worst money mistakes people make in each decade of their lives
- The principle of personal wealth explained in a chart
Featured image: Marostegui, CC BY-SA 4.0, via Wikimedia Commons.



