Building wealth or achieving financial freedom doesn’t just take studying numbers and personal finance topics. In fact, having mental and emotional control over money matters more than we think. Money problems start in our minds. Every day we fall victim to countless psychological mistakes, or cognitive biases, that damage our finances.
Below is a summary of four of these psychological traps around money, along with some additional information. I’m sure many of you will recognise yourselves in them.
4 psychological mistakes in financial education that hurt your personal finances
1. Thinking about money in relative rather than absolute terms
This bias is very common in most people, because sometimes not having it might even make you look inconsistent. Let me explain.
If you have a coffee (€1.20), practically nobody would leave the waiter a €20 tip, because that would be outrageous. But if you are buying furniture for your home or a car, it would seem silly to look for somewhere selling the same thing €20 or €50 cheaper, because we are talking about a considerable amount and the saving seems trivial.
Here is an example
You are looking for a pair of trainers and go into a shop where they cost €60. But they tell you that a shop 5 minutes away has the same trainers for €40. In other words, you would save €20. If you are like most people, you would go to the other shop to save that €20, which is the smart thing to do.
See also: The best investment advice an investor can get
Now imagine you are buying furniture for your home, and it costs €2,000. They tell you that another shop 5 minutes away has the same furniture for €1,980. If you are like most people, you wouldn’t go to the other shop to save only €20 on a purchase of that size.
That is a psychological mistake that makes us see money as something relative rather than absolute. The purchase amounts may vary considerably, but the saving is exactly the same (€20). If you wouldn’t throw €20 down a drain, why throw it away on a purchase?
See also: The best books on financial education
2. You decide to save in the moment, not in advance
Most of us have a mental mechanism that only makes us remember the umbrella when it is raining. In other words, we conclude that we should save when we already have money problems.
Even those most aware of financial education rely on their willpower. And if there is one thing we can observe, it is that willpower fails.
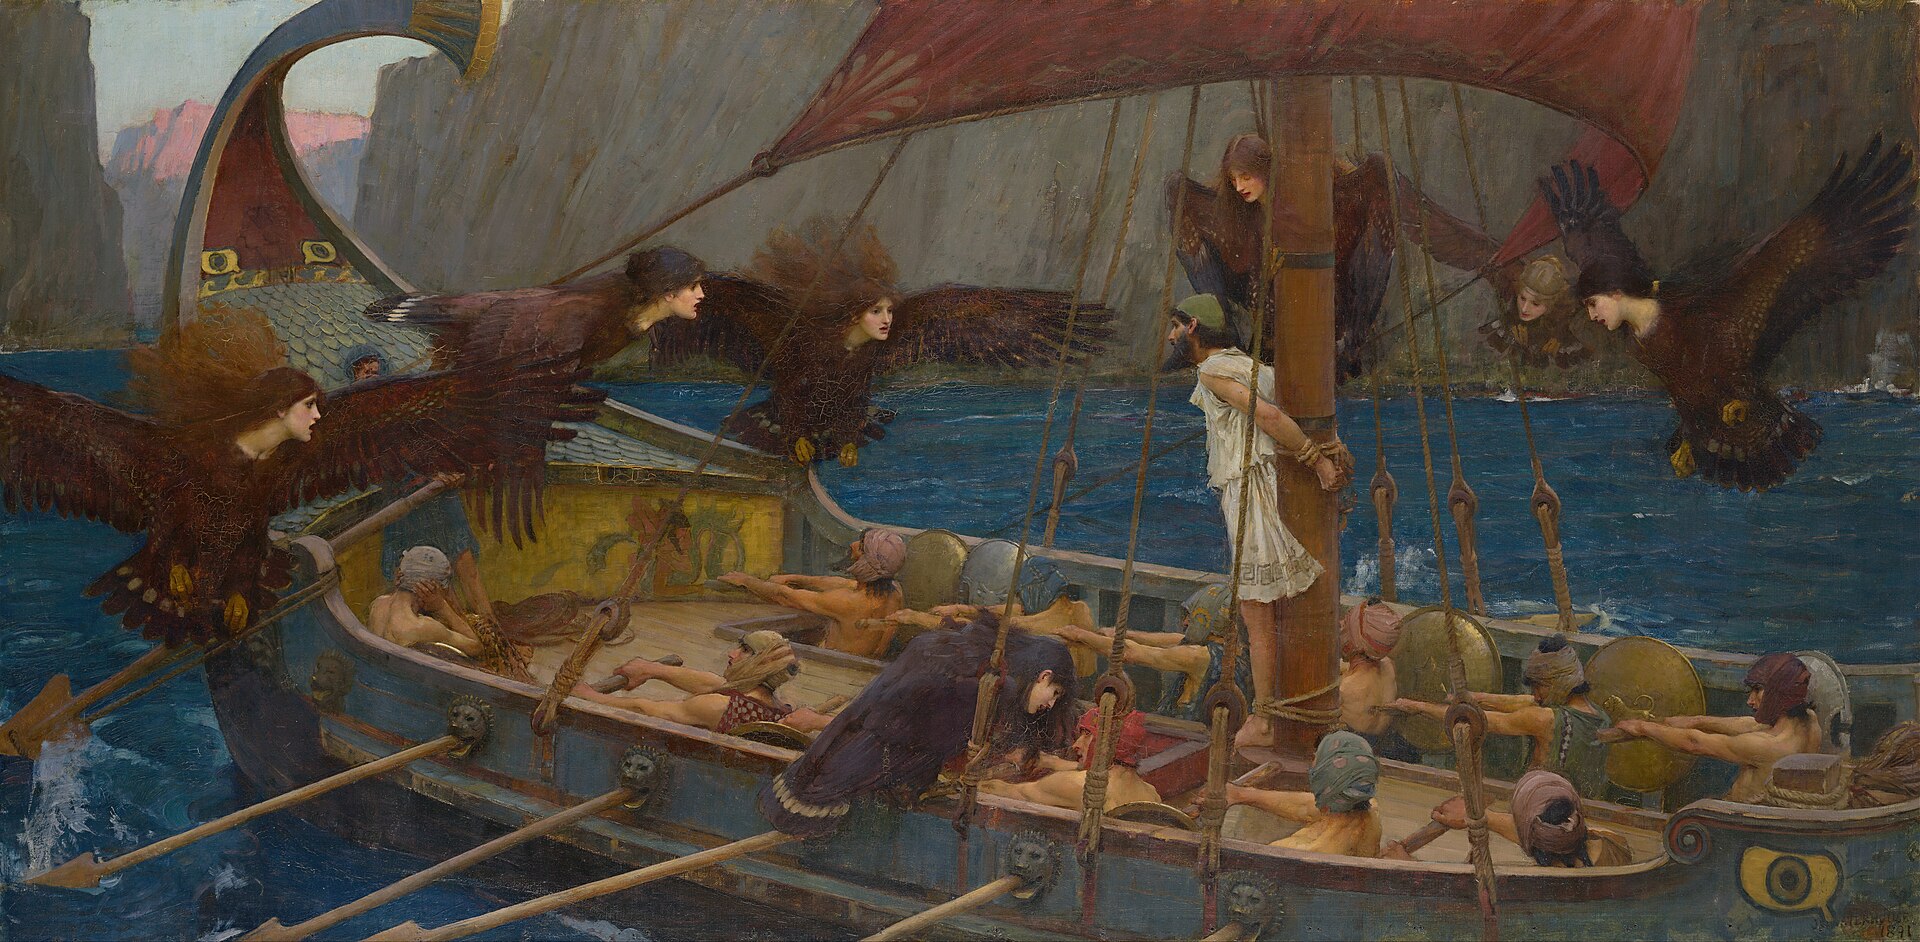
The Ulysses contract
According to mythology, Ulysses asked to be tied to the mast of his ship so that he would not succumb to the charms of the sirens.
Well, that is exactly what we should do with saving: plan it in advance and automate it. Try to make a percentage of your money go into a savings account or an investment savings account every month. How much should you save each month? That article has the answer, although it is at least 20% of your income, and ideally 30% or more.
With the Ulysses contract, what we avoid is having to draw on willpower every month to do what we should do: save. This way we use our willpower only once (the moment you decide to automate a percentage of your income for saving), and you think of it as just one more bill (a commitment) you have to meet. This is actually what is known as paying yourself first.
3. Opportunity cost
This one is simple to explain in personal finance. A very common mistake is that we don’t think about where else the money we spend could go, and that is why we spend it. In other words, if you spend €80 on a dinner or €50 on drinks one night, you are very probably not thinking about where else you could put that money to improve your personal finances.
Money you put towards one thing can no longer go towards something else. The same happens when it comes to investing in projects or improving your future. For example, if there are two things you want to do, travel to India and get a qualification from a private academy, it is clear that if you use the money to travel to India, you can no longer use that money to improve your future.
Opportunity cost is a bias that leads to a lot of headaches and regrets later on, especially when a person looks back and works out in hindsight how much they could have saved or invested if they hadn’t spent the money on certain activities.
See also: 7 creative ways to save more money
4. The sunk cost effect
This bias, combined with loss aversion and commitment bias, means that instead of analysing whether we made a good decision so that we can cut our losses, we look only at how much money and time we have already invested in that decision.
Example: a manager with a budget of 100 million euros to get a project off the ground realises, once 90 million has been spent, that the project is not going to succeed and that finishing it would be throwing money away. But since 90 million of the 100 million has already been invested, the most likely outcome is that the manager will put in the other 10 million to finish the project.
If the manager had discovered that the project was doomed when only 1 million or 10 million had been invested, they would most likely have stopped investing and written off the capital.
So, in this example, the manager is not analysing whether the decision is smart or not. In fact, they already know that the decision they made is not smart. All they are looking at is how much money they have already put into it.
This bias is present in many other areas of our lives, such as staying in a relationship because the couple have been together for 10 years, or staying in a job because you have been with the company for 20 years. We don’t tend to look to our future, but to what we have already invested in the past.
Featured image: John William Waterhouse, Public domain, via Wikimedia Commons.