Editor’s note: This article was first published in March 2012, about the measure the Spanish government had approved the previous week, the Code of Good Practice for mortgage restructuring (Royal Decree-law 6/2012). The rules were amended in later years; the requirements and terms described reflect March 2012 only.
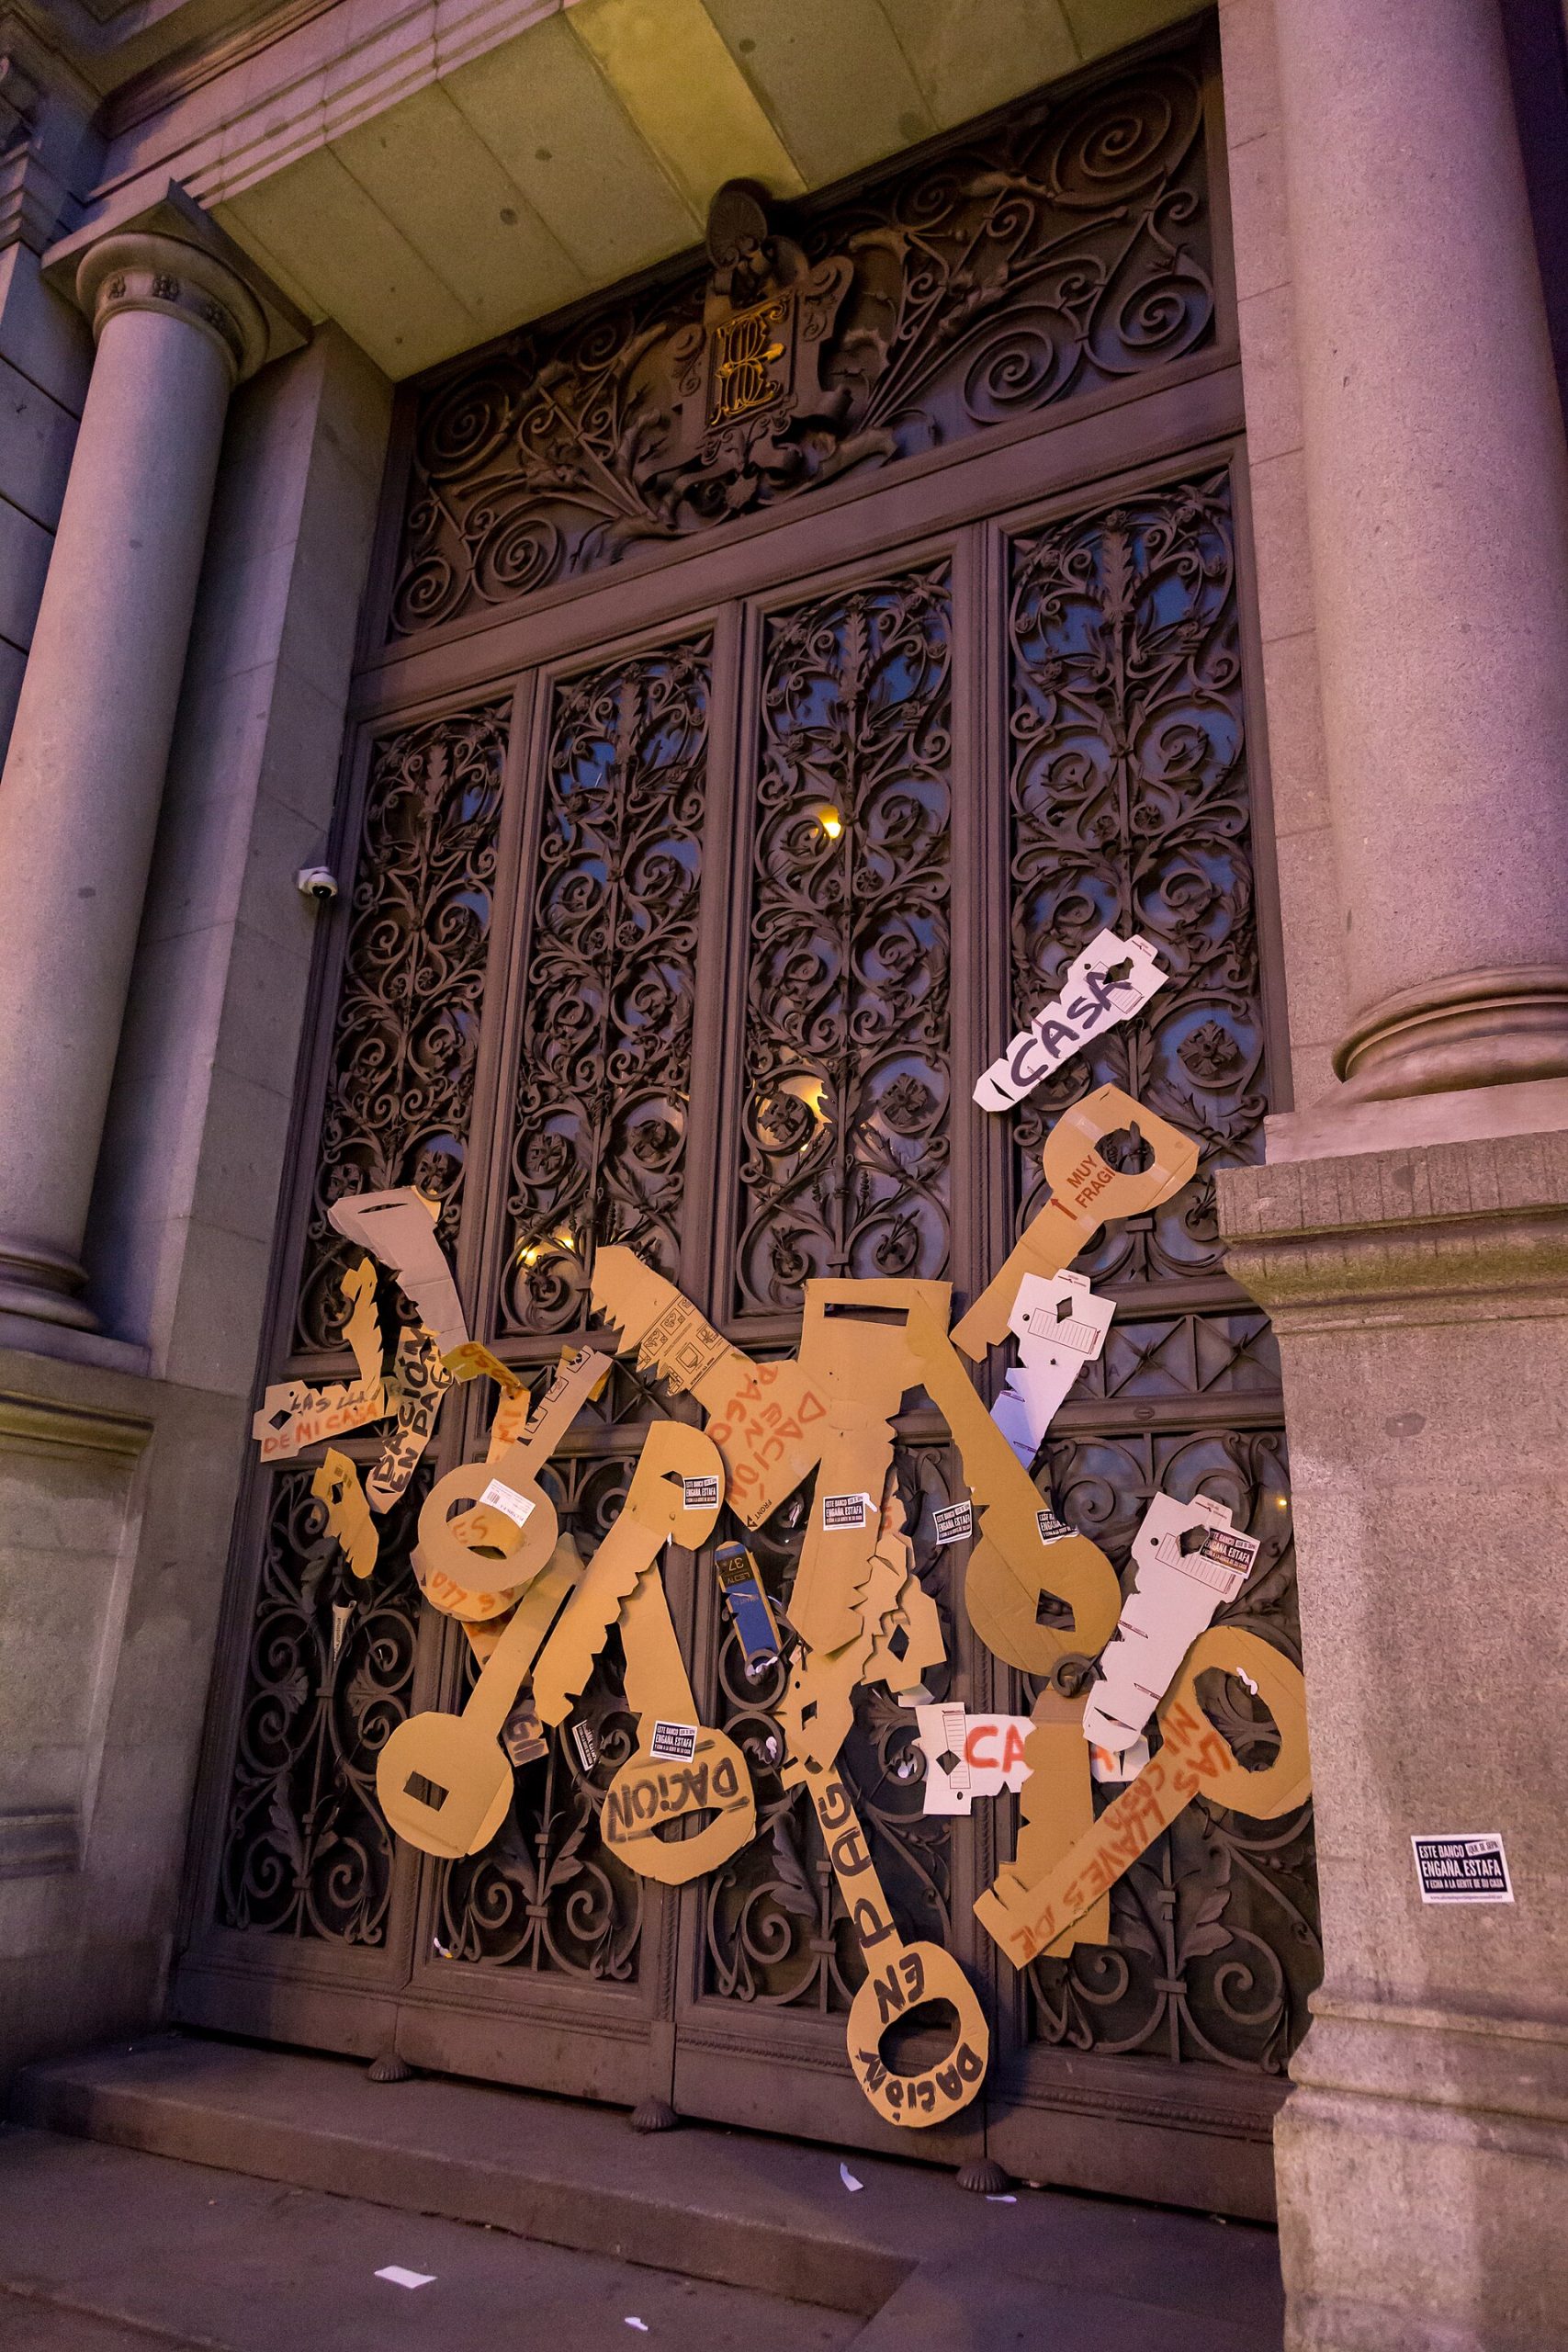
Spaniards had long been calling for dación en pago, the right to settle a mortgage debt by handing the property over to the bank. It was hard to imagine any government approving such a measure, because with dación en pago the banks would have to absorb considerable losses, given that a home is now worth much less than the mortgage they granted on it.
To our surprise, a week ago we heard that dación en pago had been approved, so I imagine many Spaniards saw a little light at the end of the tunnel. Well, once you dig into the fine print, the light goes out again: judging by the requirements, the only person who could take advantage of this solution is someone living in a cardboard box. These are some of the requirements:
0. First of all, the bank that holds your mortgage must have signed up to the Code of Good Practice.
1. Every member of the family must be unemployed, have no other assets and hold no property rights.
2. It must be the only home you own.
3. The home cannot be worth more than €200,000.
Let me stop at this point, because combined with the previous two it means that, with every family member unemployed and owning nothing else, the whole family would be living under the same roof. If a couple has two or three children, we’re talking about a flat or house with at least three bedrooms. During the property boom, €200,000 for a flat with more than two bedrooms… you rarely saw that.
4. The mortgage must not have a guarantor.
Curious, considering that the humblest families are precisely the ones who need a guarantor to get a loan in the first place.
5. The case must not already be in foreclosure proceedings.
At this stage… a very timely requirement.
6. The home cannot carry any later charges or liens.
And now comes the real bombshell: if by some chance you managed to meet these extreme requirements, don’t celebrate yet, because you still wouldn’t get dación en pago. You would first have to go through a mortgage restructuring plan, in which the bank would give you a four-year grace period on the principal at Euribor + 0.25%, plus an extension of the loan term.
If you still couldn’t pay, the bank would look at other possible write-downs. If even with those write-downs you still couldn’t afford your home, you would have 12 months to request dación en pago. Only then would the bank be obliged to grant it… provided, of course, that nothing has changed along the way for any member of the family that might somehow clash with some line of that ambiguous fine print, so hard to read and understand.
In short, there is no dación en pago as such. Once again the government has approved a measure with a big headline and a text that has nothing to do with the headline, and once again the banks win.
Featured image: Barcex, CC BY-SA 3.0, via Wikimedia Commons.