

Editor’s note: This article was first published in April 2014. Its Spain-specific examples, including preference shares sold to retail savers and Forum Filatélico, come from the post-2008 crisis. The 3% loan versus 2% deposit example reflects 2014 rates.
Being unprepared when it comes to money is already a form of personal financial suicide in itself. Today, financial education should be one of the most important subjects for anyone, young, adult or elderly, to master because, in case anyone has not noticed, the saying is true: money is neither made nor lost, it just changes hands.
That would explain why, in global financial crises, the poor get poorer while the rich come out with their wealth strengthened. And here we are not talking about crooked politicians and businesspeople, but about the genuinely rich who know how to swim in waters where the middle class drowns.
There are many mistakes people make with their personal finances, but we are going to focus only on the ones that amount to financial suicide, with ignorance and a lack of interest in learning about money as the two greatest allies of that situation.
Eight forms of financial suicide
See also: The four most striking differences between how the rich think and how everyone else does
1. Spending more than you earn
This is the main mistake of the middle and lower classes, and the global economy’s consumption rests on these social classes. Who else would buy something they do not need on credit, with money they do not have? Only a person without a solid financial education does that (and I am assuming almost all of us have done it at some point).
The expression “living beyond your means“ does not go down well with most people who now find themselves in a serious personal financial crisis. But the truth, and I am very sorry to say it, is that you could not afford to spend 30 days on holiday outside Spain, even if you were able to pay for it.
You probably could not afford the car you bought either, or the house you signed that 30-year mortgage for. You could not even afford to eat out every weekend. And how do I know you could not afford it?
See also: Are you going to give children financial education classes at school?
Because your current situation shows that you spent money you need today, failing to save when you could and falling into the trap of thinking you were a genius, when in reality you were simply riding an excellent global economic cycle of limited duration, also known as a bubble.
That is why today, if we can explain to our children the reason for the situation people are going through, we will already have given them an excellent lesson in finance.
2. Paying more interest than you earn
People do not usually give this much importance, but if we have loans on which we pay 3% and keep our savings in fixed-term deposits at 2%, we are really being foolish, and it might be a better idea to reduce or pay off that debt.
See also: Pay off debt or save and invest when extra income comes in?
As we have said on several occasions, credit cards are the cancer of our personal finances: if we cannot pay off the full balance each month, the interest that builds up against us will rarely be beaten by any investment.
3. Going into debt early
Between the ages of 20 and 30 you should not take on any kind of debt that carries interest against you. It is the perfect age to study, learn, work, save and invest part of those savings. It is even an age to take risks with part of your capital.
But it is an age to focus on getting a return on your money rather than paying interest on whatever debt you have taken on.
4. Knowing absolutely nothing
Knowing absolutely nothing about finance means that when we make money we let ourselves be advised by people we assume understand finance better than we do, and that is what leads us to buy complex, high-risk investment products, because we have confused the “bank manager-salesperson” with a financial adviser.
At other times we make the typical rookie investor’s mistakes, buying exactly the same shares as the rest of the herd, and we often fall into the mother of all investing mistakes. Remember that the advice of most great investors is not to invest in things or products you do not understand.
5. Not investing
Other people know so much about finance that they are completely averse to risk and therefore think that any investment carries some risk. And they are right, but money has to be invested in order to beat inflation, which erodes our capital. As we have said before: “if you do not invest out of fear of risk, you should know that not investing is already a big risk of constant loss.”
6. Using your home to secure loans and credit
Although it is sometimes unavoidable to put up our house as collateral to get a loan, the truth is that this is among the most common forms of financial suicide in Spain.
Many loans to start our own business are only granted because we put our home up as collateral. At other times, the house pays for a wedding or even for the holiday we can only afford by adding that credit to our mortgage.
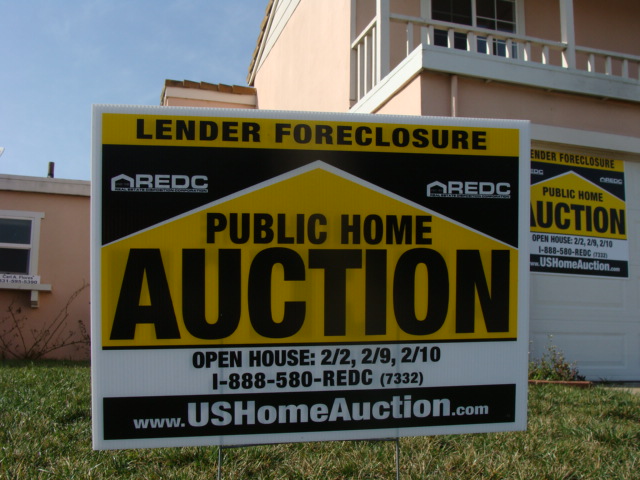
Remember that once we have paid 5, 10 or 15 years of the mortgage, if we cannot keep up the payments on a loan for which we put our home up as collateral, we risk losing the home to foreclosure, having made both the greatest financial folly and the worst investment of our lives.
7. Marriage
While marriage is one of the biggest destroyers of wealth, at other times we put businesses, bank accounts and property in our spouse’s name, always counting on “love until death do us part”. There is no need to spell out what could happen in an acrimonious divorce. When there are children involved, the spouse who does not have custody finds themselves in a highly unstable financial situation.
We cannot predict whether our marriage will last forever. A wise old man once told me that in marriage you have to look after and love your wife as if it were for life, but you have to protect your money as if you were getting divorced tomorrow. Twenty-five years later, I understand perfectly why he said it.
See also: Five conversations about money you should have with your partner before getting married
8. Bad investments at the worst time or in the worst place
People who got trapped in preferentes (the preference shares Spanish banks sold to their retail customers). Others put all their savings years ago into Forum Filatélico (a stamp investment company), and some lost their fortune investing in funds specialising in high-potential technology companies shortly before the year 2000.
Many large fortunes earned through hard work, effort and day-to-day sacrifice over decades go down the drain with a single decision: making the wrong investment when we are least diversified and betting the most capital on that one investment.
It also happens when we go all in with our capital in a completely bearish market, at the risk that some of the companies whose shares we hold end up trading at 0€.
As we can see, there are many mistakes to be made, though they are almost always rooted in a lack of knowledge.
See also: Money tips from the most successful people
Featured image: User:Brendel at en.wikipedia.org, CC BY-SA 3.0, via Wikimedia Commons.



