

Editor’s note: This article was first published in October 2015. Its return assumptions, with savings accounts at 0.5% and fixed-term deposits at 2%, reflect rates at that time, and its 5% and 9% stock market scenarios are illustrative, not guaranteed.
To build a large fortune, we need to harness the magic of compound interest, whose formula is your money × (1 + i)^n: the profits (interest) are added to the principal as you go. But what is compound interest, what does it involve and how does it really work?
Albert Einstein called this seemingly simple formula “the greatest mathematical discovery of all time.”
All that stands between you and your financial goals are four variables, which we previously called the 4 pillars of financial education
- The money you earn.
- The money you don’t spend (savings).
- The return you get on your money.
- Time (which depends on the return we get on our investment).
So the more money you invest and the sooner you start, the sooner you’ll reach certain financial goals.
Since words can’t really do justice to the magical nature of compound interest, let’s try some visuals.
This is how the magic of compound interest works
Here’s how a single €1,200 investment grows over time in four different scenarios of investment vehicles and returns, as long as the interest is added to the principal.
| Savings account (0.5%) | Fixed-term deposits (2%) | Stock market (5%) | Stock market (9%) | |
|---|---|---|---|---|
| Initial investment | 1,200 | 1,200 | 1,200 | 1,200 |
| 5 years | 1,230 | 1,325 | 1,532 | 1,846 |
| 10 years | 1,261 | 1,463 | 1,955 | 2,841 |
| 15 years | 1,293 | 1,615 | 2,495 | 4,371 |
| 25 years | 1,359 | 1,969 | 4,064 | 10,348 |
| 30 years | 1,394 | 2,174 | 5,186 | 15,921 |
| 35 years | 1,429 | 2,400 | 6,619 | 24,497 |
| 40 years | 1,465 | 2,650 | 8,448 | 37,691 |
As you can see, simply by leaving those €1,200 alone, they could turn into almost €40,000 in 40 years. You haven’t just earned interest; you’ve earned interest on the interest added to the principal. And all you had to do was invest your first paycheck and reinvest the gains every year.
See also: How to analyse a stock before investing in a company, with a free tool
Now let’s see what happens if we add a small amount every year: instead of investing €1,200 just once, we invest €1,200 every year, which is basically €100 a month.
| Savings account (0.5%) | Fixed-term deposits (2%) | Stock market (5%) | Stock market (9%) | |
|---|---|---|---|---|
| Initial investment | 1,200 | 1,200 | 1,200 | 1,200 |
| 5 years | 7,321 | 7,695 | 8,494 | 9,674 |
| 10 years | 13,596 | 14,865 | 17,803 | 22,713 |
| 15 years | 20,030 | 22,782 | 29,684 | 42,775 |
| 25 years | 33,390 | 41,174 | 64,200 | 121,136 |
| 30 years | 40,323 | 51,829 | 88,899 | 194,211 |
| 35 years | 47,432 | 63,593 | 120,423 | 306,646 |
| 40 years | 54,721 | 76,582 | 180,656 | 479,642 |
By investing €1,200 every year, we end up with almost half a million euros after 40 years. To reach a million euros you only need to save €2,500 a year (€208 a month), and at 9% interest you’ll have your million in 40 years.
In a previous article we looked at how much you need to save to make your first million by age 65. We calculated that if you were 20, you only needed to save €361 a month, assuming a 6% return. If you start at 25, you’d need to save €499. We saw how the amount you need to save to reach a million euros by 65 rises dramatically as the years go by.
(Read: The difference between starting to save at 25 and at 35)
We could also stick with the €1,200 annual contribution from the previous example but improve our investing skills. If you can beat the stock market’s average annual return, the million-euro prize is yours.
The best thing about compound interest is that it works the same way for everyone, whether you have €20 to invest or €200,000.
The story of the inventor of chess
There’s a story that I don’t think is true, but it’s often used to explain the magic of compound interest. It’s the story of the supposed inventor of chess.
The inventor went to see the emperor of China and showed him his creation, the game of chess. The emperor was so amazed that he wanted the game for himself, so he told the young inventor that if he let him have it, he would grant him a wish.
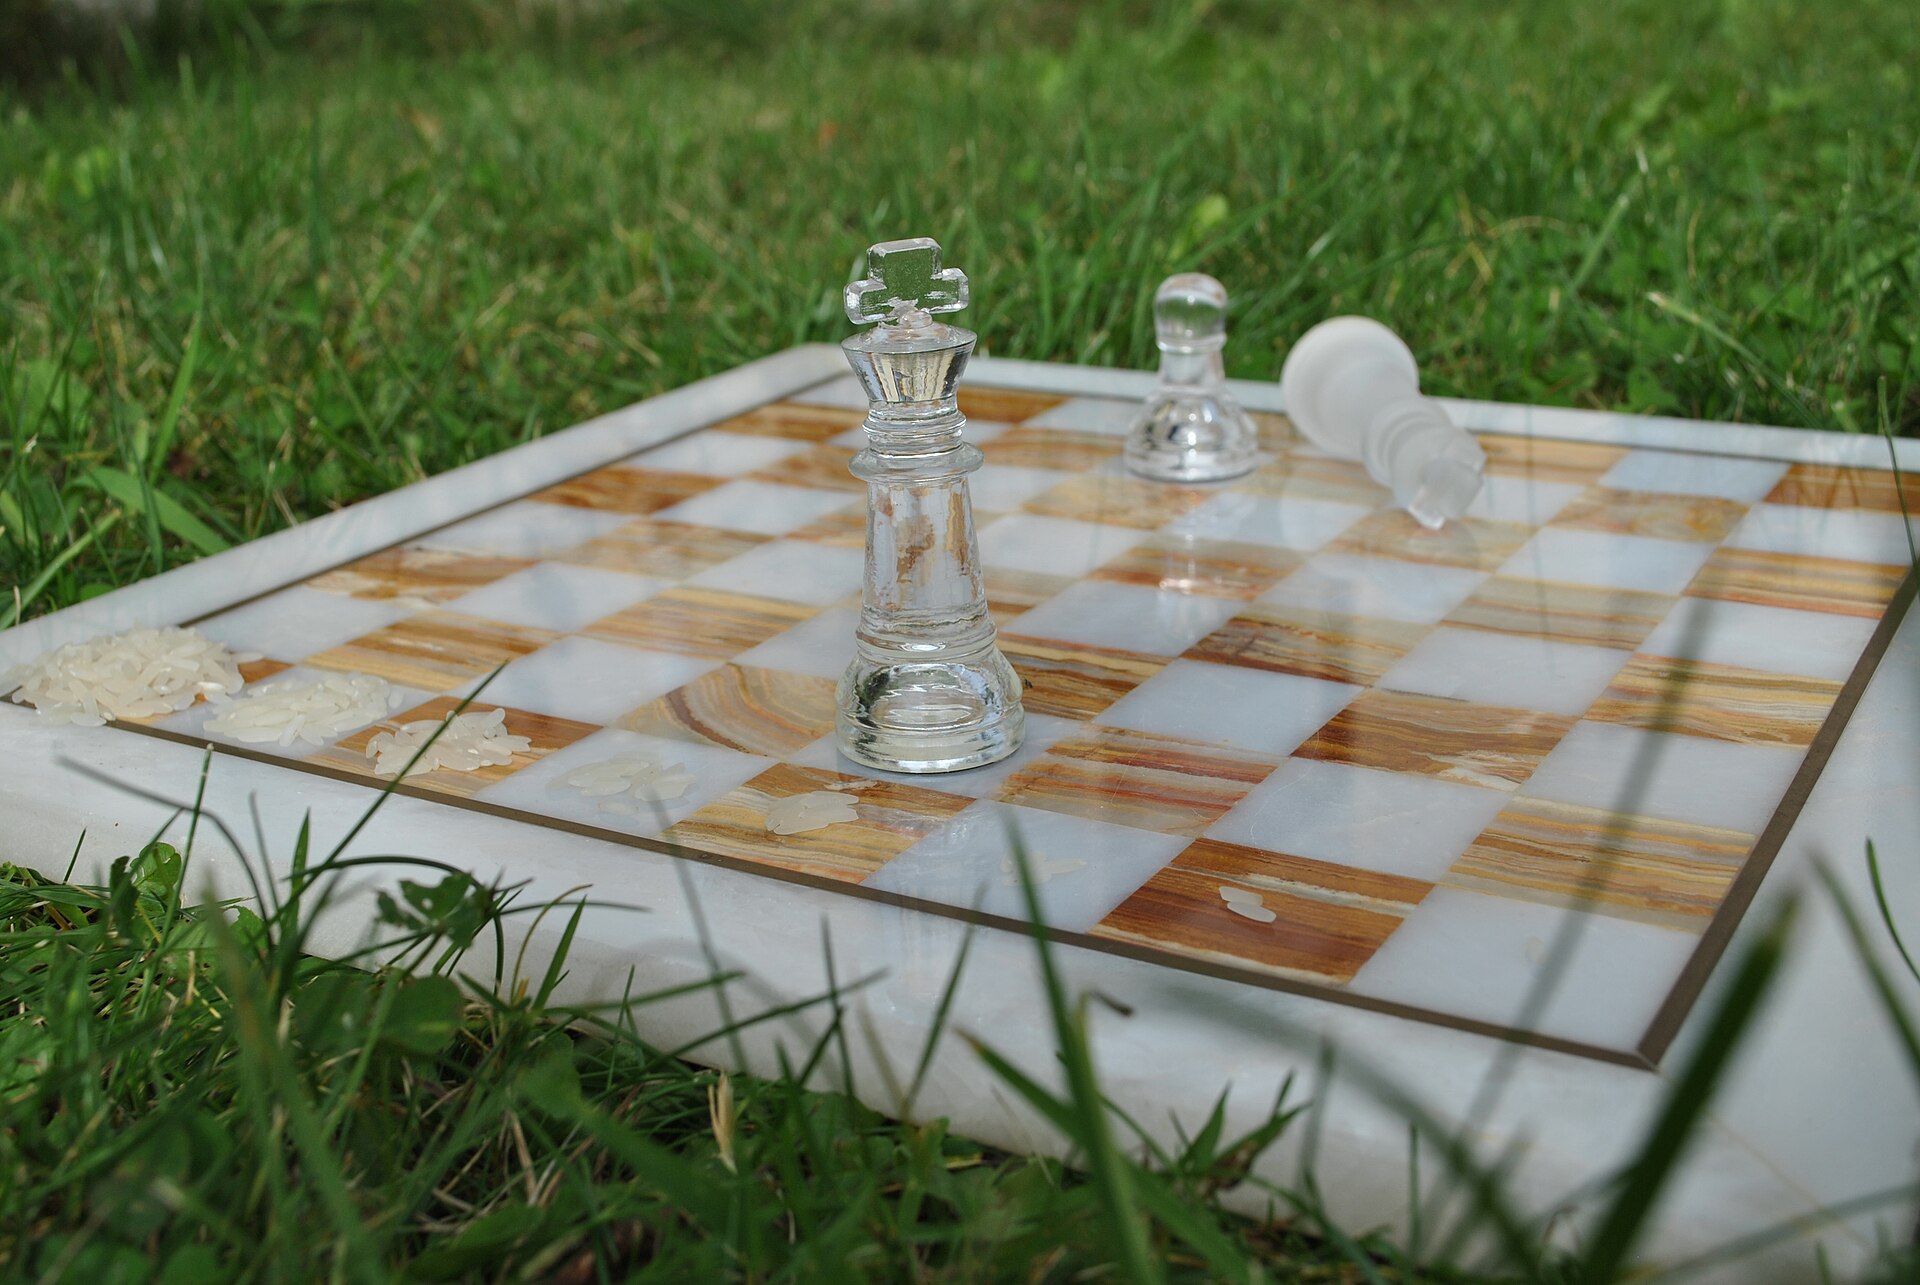
The inventor asked for something very simple: one grain of rice for the first square of the board, 2 grains for the second square, 4 for the third, 8 for the fourth, and so on, doubling the amount on each square until the last square of the board.
The emperor quickly agreed, because he thought it a very modest request. He even felt he had cheated the young man by getting his invention for a few grains of rice.
But when the emperor went to pay, working out the grains needed as the squares went up, he discovered that filling the last 10 squares of the board would take 35 quintillion grains of rice. There wasn’t enough rice in all of China to pay the inventor. The emperor then felt cheated and ordered the inventor to be killed.
If you don’t believe you can become a millionaire with just the resources you have right now, keep this story in mind.
The story of Oseola McCarty of Mississippi
This story is real. Oseola McCarty was born in Mississippi in 1908. For almost 75 years she lived in the same simple house, washing other people’s clothes for a living and putting what little money she could into savings accounts at local banks.
In the summer of 1995, Oseola made national news when she donated $150,000 to the University of Southern Mississippi to set up a scholarship fund. It soon emerged that she had managed to put together almost a quarter of a million dollars over her lifetime.
Time, a key part of the compound interest equation, helped turn her meager investments into hundreds of thousands of dollars.
After her death in 1999, one of her bankers remarked that time had been able to turn even the modest earnings on her early investments into hundreds of thousands of dollars, and that if they had managed to get her to invest in stocks, she would have ended up with millions of dollars instead of thousands.
How much we save and our time horizon are only two-thirds of the compounding equation. Oseola excelled at both. But ignoring the rate of return on her investments cost her.
Generally speaking, the more risk you’re willing to take (for example, investing in shares instead of bonds or fixed-term deposits), the higher your potential return. But risk is a four-letter word that scares a lot of people: they’re happy to settle for lower returns to avoid it.
Financial independence is just 4 variables away. So start now: save as much as you can, invest as much as you can and get as much interest on your investments as you can. Because the sooner the wonder of compound interest starts working for you, the sooner you’ll be able to reach your financial goals.
Featured image: MartinThoma, CC BY 3.0, via Wikimedia Commons.



