

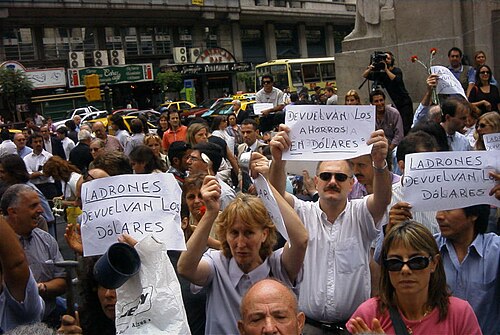
Editor’s note: This article was first published in December 2011, at the height of the euro debt crisis, when a euro break-up and a return to the peseta were being openly discussed, and while Spanish savers who had bought preference shares and subordinated debt could not get their money back.
More and more people in Spain share this worry: “What would be the best way to protect my money if we ended up in a situation like the one Argentina went through?“
First of all, the chances of that happening in Spain (or anywhere in Europe) are very slim. In fact, it’s unlikely, though not impossible. The fear of a possible “corralito” (the freeze on bank withdrawals Argentina imposed in 2001) has grown because thousands of savers put their money into “guaranteed return” products at financial institutions and now can’t get it back.
Most of them, of course, are small investors who bought preference shares, convertible bonds and subordinated debt. We covered this in our article “Safe, profitable investments and their small print”. Basically, these savers didn’t realize that the institution would only pay out depending on its results. If the results aren’t good, the institution doesn’t have to pay, but that’s another story.
So is it likely that the euro will disappear, that we’ll go back to the peseta (or another currency), that our money will lose value, that banks won’t let us withdraw our savings and that we’ll live through something like Argentina? No, it isn’t likely. Is it possible? Yes, it could be. With that said, let’s look at how we could protect our money.
How to protect our savings
I’ve seen all kinds of advice from experts, some of it so professional that they forget one of the simplest and most workable tips for the small saver. Clearly, the way to move your money can’t be the same for someone with more than €500,000 saved as for someone with €20,000 in their account.
I’ve even seen it suggested that one way to protect your savings is to put them in the stock market or invest in gold. With all due respect, for a small saver who is afraid of a “corralito”, has never invested in the stock market and doesn’t understand anything about investing, that would be financial suicide. Is gold in a bubble right now? Which stock should I invest in? After all, in a bankruptcy, the first stocks to avoid are those of financial institutions exposed to the country in question.
1. Under the mattress
For the small saver, without any doubt, the best way to protect money in this situation would be cash (under the mattress). Some will say: “But you told us money should be invested so that inflation doesn’t eat away our savings.” I completely agree, but we’ll now see why, if it came to that, for small amounts (€15,000–€50,000) it’s the most reliable, workable, useful and cheapest option, bearing in mind that we run the risk of theft. Experts don’t usually give this advice, because if many savers became afraid of a “corralito”, their very fear and a mass withdrawal of money from the banks could cause chaos in the financial system.
2. A foreign-currency current account
This is what experts recommend most, because it’s convenient and can be done at any Spanish bank. But few warn you that if you prepare for a “corralito” and it never happens, you’ll have lost a lot of money in fees and exchange-rate differences. And don’t forget that if the euro disappeared, the government could automatically convert that account into pesetas. In short: it isn’t a safe way to protect your savings.
3. Opening an account in Switzerland
Another very popular tip that’s also of very little use to the small saver. If I remember correctly, you have to open a Swiss account in person; in other words, you can’t do it online. If your fear is that your money will lose value, the trip to Switzerland alone is an expense that will eat into your savings. Not to mention that maintaining a Swiss account is quite expensive. For large sums, however, in my personal view it would without any doubt be the best way to protect your money.
4. An account abroad as a non-resident
Finding a country outside the European Union and opening an account as a non-resident… would be of little use if countries agreed among themselves on restrictions to prevent capital flight. On top of that, the tax authorities would claim tax on the returns.
As you can see, if the serious situation we’re talking about ever came to pass, there’s no 100% safe method for the small saver. In fact, if you ask experts how to protect your savings in that situation, they usually point you towards some kind of investment: “Invest in stocks, invest in gold, invest in corporate debt, etc.” Investing in variable-income products carries risks.
Some readers have asked me whether renting a safe deposit box at a bank would be a good option. The answer is no, because if it came to that, the government could search the boxes to seize the cash, and renting a safe deposit box also has an annual cost.
In short
If your savings don’t exceed €50,000, the safest place for you is the mattress. For large sums (over €500,000), the safest place is Switzerland.
Featured image: Taken by the uploader, w:es:Usuario:Barcex, CC BY-SA 3.0, via Wikimedia Commons.



