Editor’s note: This article was first published in March 2014; the share prices, dividend yields and dividend growth figures it cites for UPS, Baytex and JPMorgan are from that time, and its forecast of an S&P 500 correction in 2014 has since expired. These stock picks date from March 2014 and are kept as a historical record. They are not investment advice.
After the S&P 500’s 30% rise over the past year, the managers at McLean & Partners Wealth Management say there is no rush to buy cheap stocks, because there aren’t that many cheap stocks left.
These managers are aware that the S&P 500 is due a correction sooner rather than later, so for now they stress the need to hold cash for when that correction comes, which we should see this year, 2014.
Even so, McLean & Partners have a group of stocks for their high-net-worth investors, stocks that could be added to our long-term portfolio regardless of price swings. These are stocks on which we could calmly apply the DCA investment strategy, since they are large- and mid-cap companies with solid balance sheets and growing cash flow to fund future dividend increases and share buyback programmes. McLean & Partners look for companies with a sustainable competitive advantage or a healthy balance sheet with plenty of cash. And these would be three of the stocks they advise including in our portfolio.
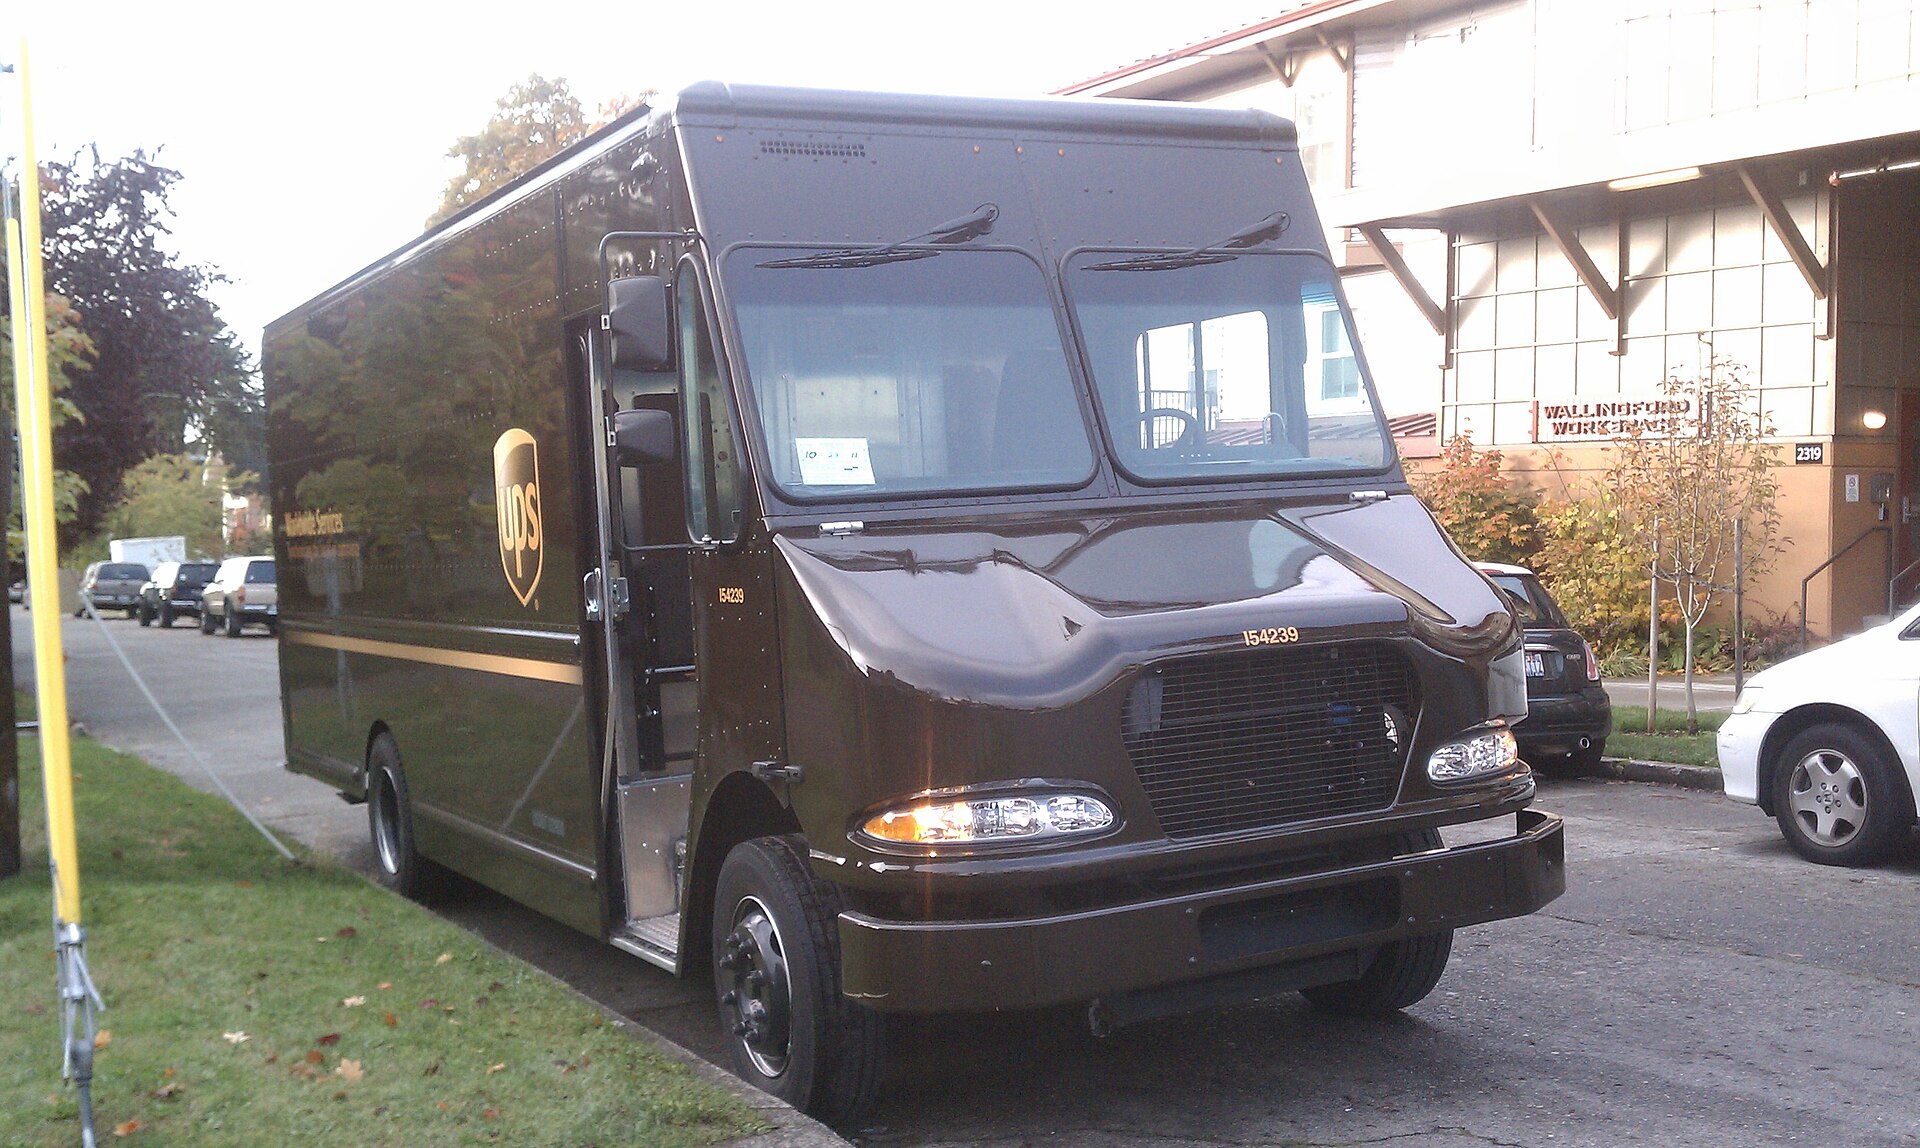
United Parcel Service (UPS)
- Current price: $95.78
- Dividend yield: 2.8%
- The dividend has grown 8.7% over the past three years.
As a shipping company, UPS is benefiting from the global growth of e-commerce. What’s more, the company is earning growing revenue from its contract logistics division, which runs outsourced supply chain, distribution and transport operations for a wide range of clients. “We like the fact that employees own 23% of the company, so their interests are aligned with those of investors.” It trades at a P/E of 20, but that is acceptable given the company’s solid growth prospects, the investment firm says.
Baytex Energy Corp (Canada)
- Current price: $41.04 (Canada)
- Dividend yield: 6.4%
- The dividend has been raised by 6.3%.
This month Baytex launched a 1.8 billion offer for Australia’s Aurora Oil & Gas, a deal in which investors will see an immediate benefit. It is expected to close in May, and the company has promised to raise its dividend by 9%. The managers praise the company’s solid management and disciplined approach to capital allocation.
JPMorgan Chase
- Price: $56.21 (US)
- Dividend yield: 2.6%
- The dividend has grown 93% over the past three years.
JPMorgan is currently the largest bank in the United States by assets. The bank is expected to keep growing through mergers, acquisitions and rising wealth management revenue. The company cut its dividend by 87% during the financial crisis, but after reinstating it, it brought it back to where it had been. As the economy grows, the bank is expected to keep raising its dividend.
*Worth noting about this stock: it faces significant resistance around $64, which could act as a brake on the share price. Of course, since that is its all-time high, if it manages to break through that resistance the stock could soar into blue-sky territory, with no resistance above it.
For our part, we still recommend three stocks for conservative long-term investors, for their growth prospects as well as their dividends.
Featured image: Atomic Taco from Seattle, WA, USA, CC BY-SA 2.0, via Wikimedia Commons.